Key Takeaways:
- Know what it means to defer a mortgage payment:
Refinancing may give you more time before your first scheduled payment on the new loan is due, but it doesn’t eliminate the payment or interest. - Understand how your payment timing changes:
Your refinance creates a new loan with a new payment schedule, which may shift when your next regularly scheduled mortgage payment is due. - Give your budget some breathing room:
The time before your first scheduled payment may provide temporary flexibility for savings, bills, debt, or other financial priorities. - Look beyond payment flexibility:
Refinancing may also provide opportunities to change your interest rate, adjust your loan term, or access available home equity. - Consider the bigger financial picture:
Your rate, payment, loan term, closing costs, available equity, and long-term goals can all help determine whether refinancing makes sense. - Start with a free mortgage checkup:
An AmeriHome Home Loan Expert can help you review your current mortgage and explore refinance options that may better fit your financial goals.
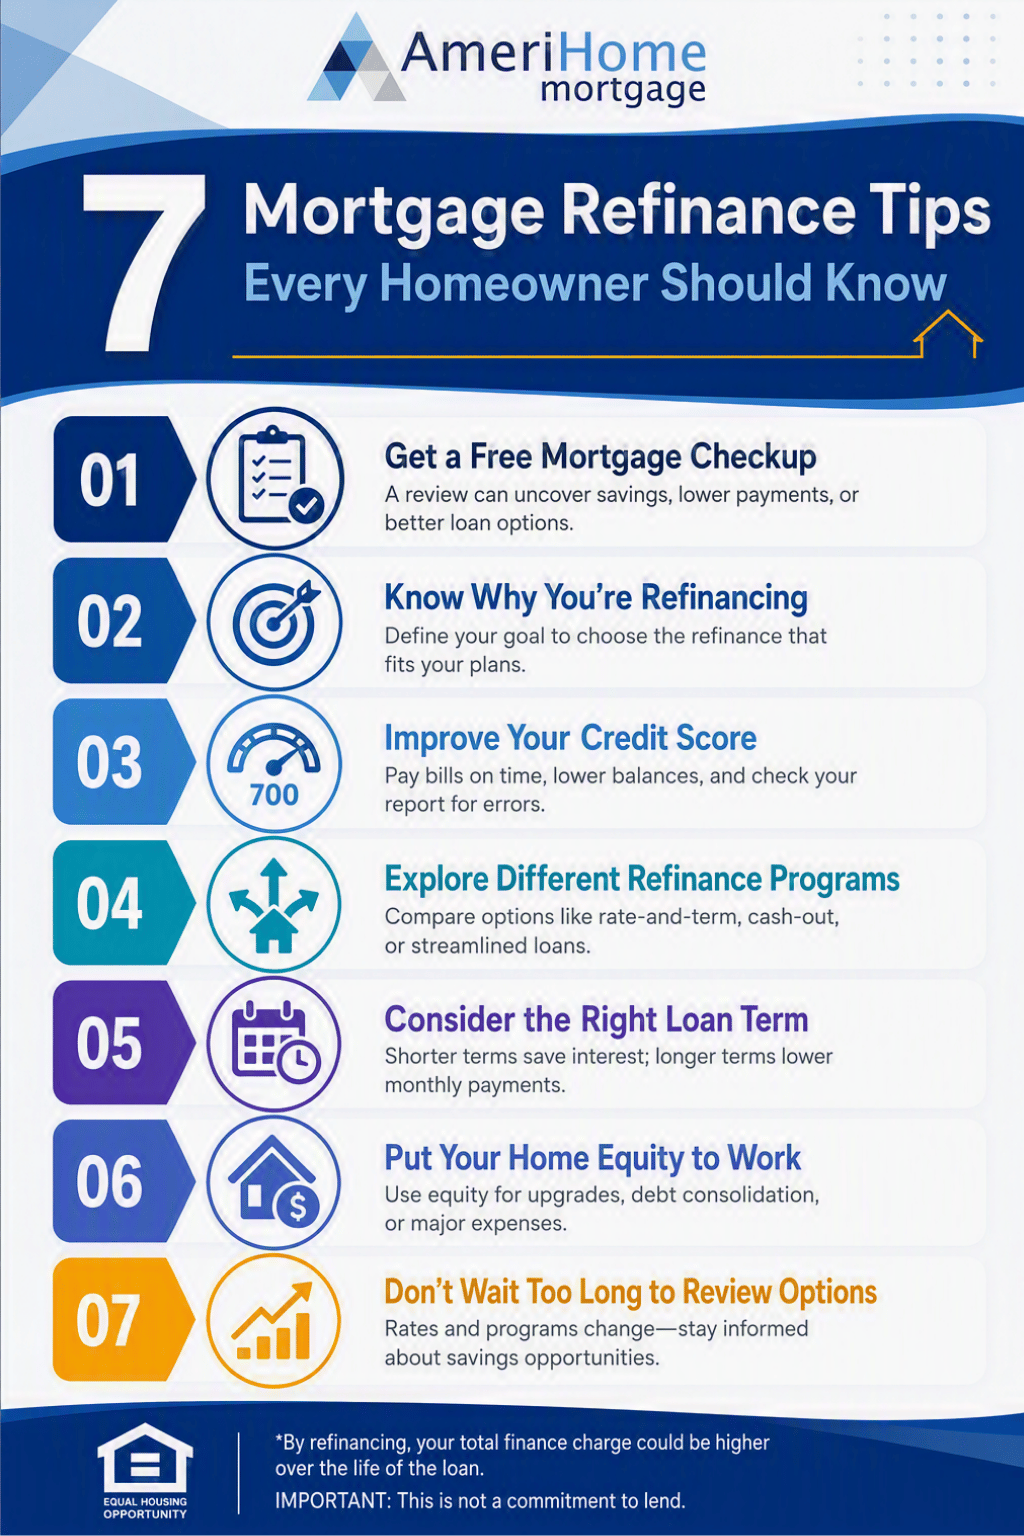
How Can Refinancing Impact Your Next Mortgage Payment?
How Can Refinancing Impact Your Next Mortgage Payment?
Between groceries, insurance, utilities, credit cards, and other everyday expenses, finding a little extra room in your monthly budget can make a big impact. If you’re thinking about refinancing your home, there may be another potential benefit to consider beyond changing your mortgage rate or loan terms like the timing of your next mortgage payment.
When you refinance, your current mortgage is paid off and replaced with a new home loan. Because the new loan comes with a new payment schedule, there may be a period of time between your refinance closing and when your first payment on the new mortgage is due. For homeowners looking for more financial flexibility, that timing could provide some welcome breathing room.
Do You Really Defer A Mortgage Payment When You Refinance?
Do You Really Defer A Mortgage Payment When You Refinance?
When your refinance closes, your existing mortgage is paid off and the new mortgage begins. Depending on the timing of your closing and the terms of your new loan, your first regularly scheduled payment on the new mortgage may not be due right away.
However, this doesn’t mean you’re receiving a free mortgage payment or that interest simply disappears. Interest between the closing date and the period covered by your first monthly payment may be accounted for through prepaid interest at closing.
The Consumer Financial Protection Bureau explains that prepaid interest charges cover daily interest that accrues between your mortgage closing date and the period covered by your first monthly mortgage payment.
At A Glance
How Does Deferring Your Next Mortgage Payment Work?
How Does Deferring Your Next Mortgage Payment Work?
The timing comes down to how mortgage payments are structured. When you complete a refinance, your old mortgage is paid off as part of the transaction, and you’re issued a new loan. Your new loan then follows its own payment schedule.
Depending on when you close, this could create a window before your first regularly scheduled payment is due. Instead of viewing this as a payment that disappears, think of it as a shift in when your next mortgage payment is due.
At A Glance
Refinancing replaces your current mortgage with a new loan and a new payment schedule. Depending on when you close, this may shift the timing of your next scheduled mortgage payment, giving you more time before it’s due.
What Could You Do With The Extra Breathing Room?
What Could You Do With The Extra Breathing Room?
Not having a regularly scheduled mortgage payment due immediately after refinancing could provide temporary flexibility in your monthly cash flow.
For some homeowners, that extra room in the budget might make it easier to replenish emergency savings or address upcoming household expenses. Others may choose to put those funds toward higher-interest debt, home improvements, insurance costs, or another financial priority.
Of course, every homeowner’s situation is different. The important thing is to look at the short-term payment timing alongside the overall costs and potential long-term benefits of refinancing.
At A Glance
The extra time before your next scheduled mortgage payment may give you greater flexibility to focus on other financial priorities. Consider this short-term breathing room alongside the overall costs and potential long-term benefits of refinancing.
Refinancing May Offer More Than Payment Flexibility
Refinancing May Offer More Than Payment Flexibility
The timing of your next payment is only one consideration. A refinance may also give you an opportunity to restructure your mortgage around your current financial goals.
Depending on your current loan and the refinance options available to you, you may be able to secure a different interest rate, adjust the length of your loan, or change your monthly principal and interest payment.
Homeowners who have built equity may also consider a cash-out refinance. With a cash-out refinance, you’re replacing your existing mortgage with a new, larger loan and accessing a portion of your available home equity as cash at closing. That money could potentially be used for home improvements, debt consolidation, major expenses, or other financial needs.
Because refinancing changes your mortgage, it’s important to consider both the immediate benefits and the longer-term costs before deciding whether it’s right for you.
At A Glance
A cash-out refinance or second-lien mortgage may let eligible homeowners use equity for major expenses. Compare how each option changes your total debt, monthly payments, rate, term, and closing costs. Borrow only what supports a clear purpose and fits comfortably within your budget.
Should You Refinance Just To Defer Your Next Payment?
Should You Refinance Just To Defer Your Next Payment?
Deferring your next scheduled mortgage payment can be an attractive benefit, but it shouldn’t be the only reason to refinance.
Your current interest rate, new loan rate, closing costs, loan term, monthly payment, available equity, and how long you plan to stay in your home can all affect whether refinancing makes financial sense.
That’s why it can be helpful to look at your mortgage as part of your larger financial picture. What worked when you originally purchased or refinanced your home may not be the best fit for where you are today.
At A Glance
Deferring your next scheduled payment may be a helpful refinance benefit, but it’s only one part of the decision. Consider your rate, payment, loan term, closing costs, available equity, and long-term financial goals to determine whether refinancing is the right fit for you.
Could Refinancing Make Sense For You?
Could Refinancing Make Sense For You?
A refinance could potentially offer more than a new rate. Depending on your situation and loan terms, you may be able to defer your next scheduled mortgage payment, adjust your loan to better fit your current goals, or access available home equity. If your financial needs have changed, it may be a good time to take another look at your mortgage. At AmeriHome, we offer a free mortgage checkup with a Home Loan Expert who can help you explore your money-saving options.
At A Glance
Refinancing may offer more than a new rate, from changing the timing of your next scheduled payment to accessing available home equity. A Free Mortgage Checkup can help you explore your options and see whether a new loan better fits your current financial goals.
Next Steps
Next Steps
1. Start With A Free Mortgage Checkup:
Connect with an AmeriHome Home Loan Expert to review your current mortgage and discuss whether refinancing could better fit your financial goals.
2. Explore Your Refinance Options:
Compare potential rates, loan terms, monthly payments, and costs to understand how a new mortgage could change your overall financial picture.
3. Understand Your New Payment Timeline:
Review your estimated closing date and first payment due date so you know how refinancing could impact the timing of your next scheduled mortgage payment.
Frequently Asked Questions
Frequently Asked Questions
Can refinancing defer my next mortgage payment?
Direct Answer: Depending on your closing date and loan terms, your first regularly scheduled payment on the new mortgage may not be due immediately after refinancing. The timing changes because your existing mortgage is paid off and replaced with a new loan and payment schedule.
When is my first mortgage payment due after refinancing?
Direct Answer: Your first payment due date depends on your refinance closing date and the terms of your new loan. Review your loan documents to confirm the exact due date for your first scheduled payment.
Do I still pay interest if my next mortgage payment is deferred?
Direct Answer: Yes. Deferring the timing of your next scheduled payment does not mean interest disappears. Interest between your closing date and the period covered by your first monthly payment may be accounted for through prepaid interest at closing.
Can refinancing help give me more room in my monthly budget?
Direct Answer: Refinancing may provide temporary cash-flow flexibility if there is additional time before your first scheduled payment is due. A refinance may also change your monthly principal and interest payment depending on your new interest rate, loan amount, and loan term.
Can I access my home equity when I refinance?
Direct Answer: Eligible homeowners may be able to access a portion of their available home equity through a cash-out refinance. A cash-out refinance replaces your current mortgage with a larger loan and provides eligible proceeds after applicable costs and payoffs.
How do I know if refinancing is right for me?
Direct Answer: Start by comparing your existing mortgage with potential refinance options, including the rate, payment, term, costs, and your financial goals. An AmeriHome Home Loan Expert can also review your current loan as part of a Free Mortgage Checkup and discuss potential refinance options.
Looking to start saving today on your home loan? Let’s upgrade your mortgage and put money back in your wallet with a new Purchase or Refinance Loan.*
6 Money-Saving Tips To Start Today:
 |
Pay Off Your Loan Sooner Switch to shorter loan terms to save on interest.* |
|
Lower Your Monthly Payment Refinance with longer terms, so more money stays in your wallet.* |
|
Consolidate Debt Cash-out to reduce high-interest credit card debt. |
|
Pay For Larger Expenses Invest in your home with updates that will yield a higher return should you decide to sell in the future. |
|
Get Extra Savings After you have financed a home with us once, save up to $750 on all your future refinances and new home purchase loans with your AmeriWallet Benefits.** |
If you are interested in learning more about how a refinance or new home purchase loan can benefit you, just give us a call at 877.715.9908 or get your instant rate quote here.
Imagine The Possibilities With Your Better Home Loan!
*By refinancing, your total finance charge could be higher over the life of the loan.
**As a member of the AmeriHome family, borrowers are part of the AmeriWallet Rewards program. If you completed a home loan with us once, you will qualify for a $750 lender credit for all of your future refinances or home purchases done with AmeriHome, for any property you own. To qualify for this offer, you must have previously financed the purchase of a home or refinanced with AmeriHome. You have financed with AmeriHome when AmeriHome Mortgage Company, LLC appears on the previous Promissory Note for your loan, and you are listed as a borrower on the Note. Credits will be applied only if your loan closes with AmeriHome. This offer can not be combined with any other offers and is not applicable for FHA Streamline, or VA IRRRL Refinance transactions. Other restrictions may apply. Terms and conditions are subject to change. AmeriWallet Rewards program is subject to termination without notice.