Key Takeaways
- What Is PMI?
Understanding Private Mortgage Insurance (PMI). - Reduce Principal Balance To 80%
To request PMI removal. - Reach 78% Of The Original Loan Amount
You can remove PMI when your loan balance reaches 78% of the original loan amount. - Loan Term Milestone
PMI can drop off the month after you reach the midpoint of your loan term. - Refinance Your Mortgage
Refinancing can enable you to remove PMI payments.
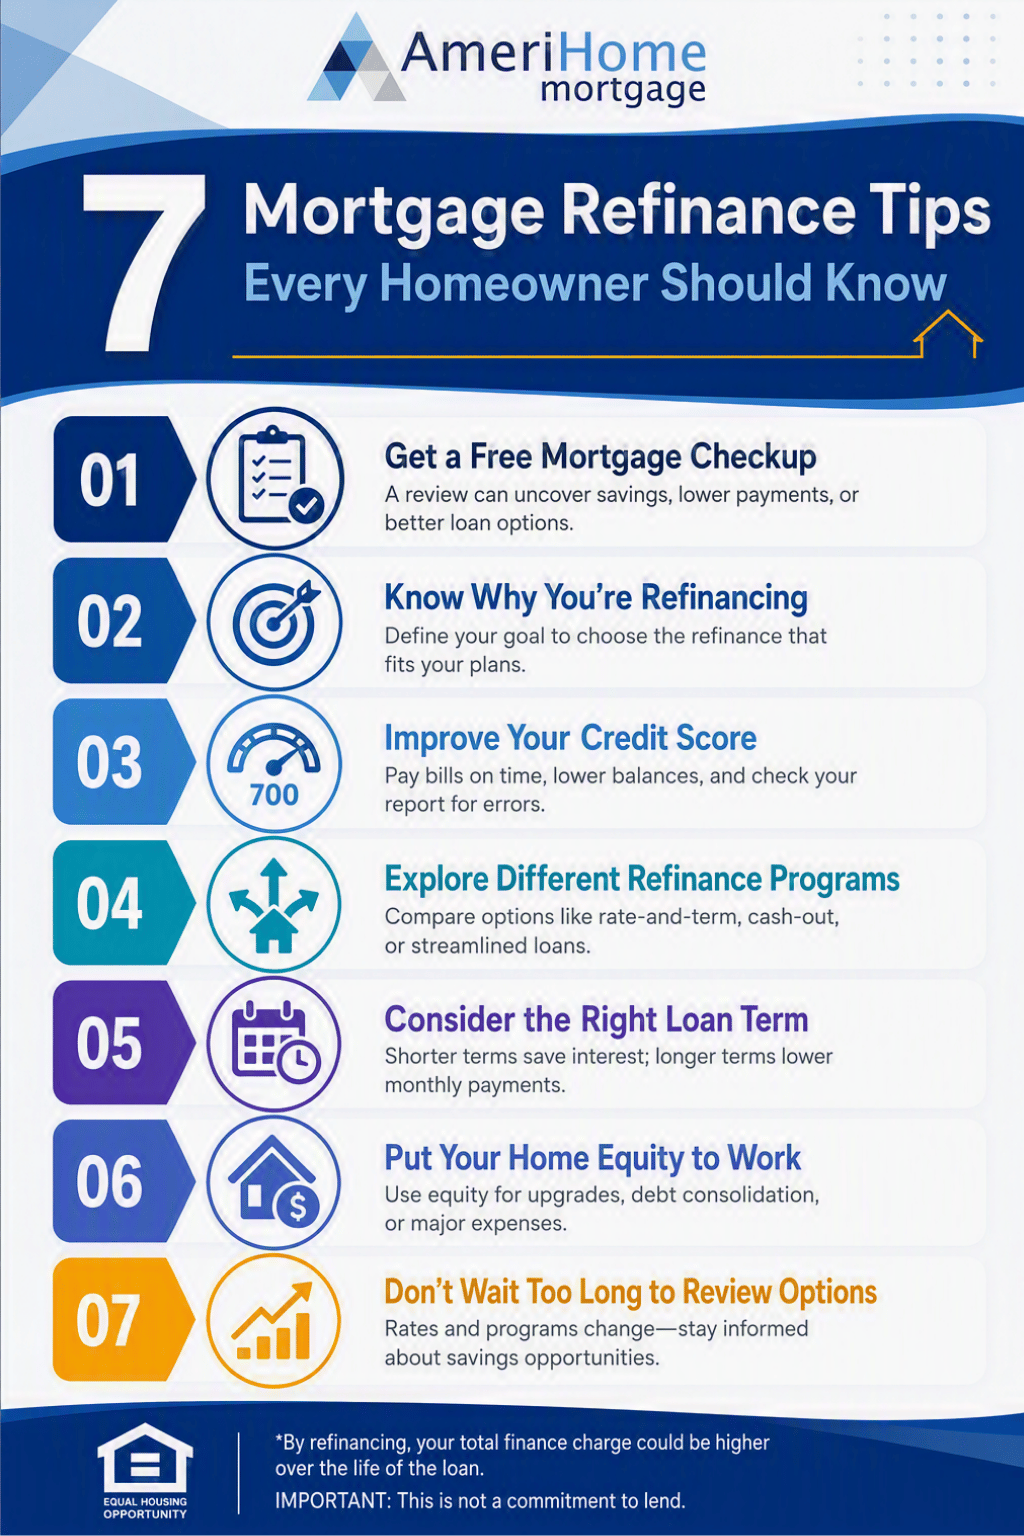
Removing PMI Payments To Save Money On Your Monthly Mortgage Payment
Removing PMI Payments To Save Money On Your Monthly Mortgage Payment
Private Mortgage Insurance (PMI) is a common cost for homeowners, but it doesn’t have to be permanent. Here are some ways you can remove PMI payments from your mortgage and save more money sooner than you might think.
What Is PMI?
What Is PMI?
PMI is an insurance policy that protects lenders in the event that a homeowner defaults on their loan. It’s required when down payments amount to less than 20% of the home’s purchase price. Actual payment amounts depend on various factors such as mortgage terms and remaining balance.
There is a point at which removing PMI is possible, and dropping it can be advantageous for you and save you money over the life of your loan. The following options coincide with Consumer Financial Protection Bureau (CFPB) guidelines, and can help you eliminate PMI.
At A Glance
PMI is insurance that protects the lender if a borrower defaults on their mortgage. It’s typically required when a down payment is less than 20%. As you build equity in your home, you may become eligible to remove PMI, which can lower your monthly payment. The options below may help eligible homeowners eliminate PMI based on CFPB guidelines.
Reduce Principal Balance To 80%
Reduce Principal Balance To 80%
Equity is measured by the difference between the value of your home and what you owe on your mortgage, and it is essential for PMI removal. Upon reducing your principal balance to 80% of the home’s original value (meaning you’ve reached 20% equity), you can then ask your lender to remove PMI from your mortgage. This can occur on the date your principal balance is scheduled to hit 80%. As long as you submit the request in writing, are current on payments, have a solid payment history, don’t have any junior liens on the property, and your home’s value hasn’t dropped below its original purchase price, you should be good to go.
At A Glance
Reach 78% Of The Original Loan Amount
Reach 78% Of The Original Loan Amount
Another threshold to keep in mind is when your loan balance reaches 78% of the original loan amount, which corresponds to 22% equity. On the date that you reach this milestone, PMI can be terminated as long as you are current on your payments. You can reach this point faster by making occasional extra payments toward your mortgage. If that’s not possible, simply continue making your regular payments and over time, you’ll build enough equity to remove PMI.
Direct Answer
Loan Term Milestone
Loan Term Milestone
Even if you haven’t reached 22% equity, PMI can drop off the month after you reach the midpoint of your loan term. As long as you’re up to date on payments, this would happen (for example) at year 15 of a 30-year mortgage. CFPB guidelines state that this method for ending PMI is “more likely to occur for people who have a mortgage with an interest-only period, principal forbearance, or a balloon payment.” Stay consistent on those mortgage payments and you’ll be on track to save cash!
Direct Answer
Refinance Your Mortgage
Refinance Your Mortgage
Refinancing is a powerful tool that can help you quickly reach the equity needed for PMI removal, especially if your home’s value has increased over time. By refinancing, you replace your current mortgage with a new one. If the new loan starts with at least 20% equity, PMI is no longer required. Plus, choosing a shorter loan term can help you build equity even faster and drop PMI sooner as a result.
Keep in mind: If you have an FHA loan, the only way to remove PMI is by refinancing your mortgage. If you’re ready to explore your options, give us a call at 877.715.9908 to learn more about the process from one of our Home Loan Experts!
At A Glance
Frequently Asked Questions
Frequently Asked Questions
When can I request PMI removal?
When is PMI automatically removed?
PMI will be automatically removed when your mortgage balance reaches 78% of your home’s original value, as long as you’re current on your payments.
Can I remove PMI before reaching 20% equity?
In some cases, PMI may be removed if your home’s value has increased significantly and you can demonstrate sufficient equity through a new appraisal.
Does PMI automatically go away at the midpoint of my loan?
Can refinancing help remove PMI?
Yes. If refinancing gives you at least 20% equity in your home, PMI is typically no longer required. For FHA loans, refinancing is generally the primary way to eliminate mortgage insurance.
Looking to start saving today on your home loan? Let’s upgrade your mortgage and put money back in your wallet with a new Purchase or Refinance Loan.*
6 Money-Saving Tips To Start Today:
 |
Pay Off Your Loan Sooner Switch to shorter loan terms to save on interest.* |
|
Lower Your Monthly Payment Refinance with longer terms, so more money stays in your wallet.* |
|
Consolidate Debt Cash-out to reduce high-interest credit card debt. |
|
Pay For Larger Expenses Invest in your home with updates that will yield a higher return should you decide to sell in the future. |
|
Get Extra Savings After you have financed a home with us once, save up to $750 on all your future refinances and new home purchase loans with your AmeriWallet Benefits.** |
If you are interested in learning more about how a refinance or new home purchase loan can benefit you, just give us a call at 877.715.9908 or get your instant rate quote here.
Imagine The Possibilities With Your Better Home Loan!
*By refinancing, your total finance charge could be higher over the life of the loan.
**As a member of the AmeriHome family, borrowers are part of the AmeriWallet Rewards program. If you completed a home loan with us once, you will qualify for a $750 lender credit for all of your future refinances or home purchases done with AmeriHome, for any property you own. To qualify for this offer, you must have previously financed the purchase of a home or refinanced with AmeriHome. You have financed with AmeriHome when AmeriHome Mortgage Company, LLC appears on the previous Promissory Note for your loan, and you are listed as a borrower on the Note. Credits will be applied only if your loan closes with AmeriHome. This offer can not be combined with any other offers and is not applicable for FHA Streamline, or VA IRRRL Refinance transactions. Other restrictions may apply. Terms and conditions are subject to change. AmeriWallet Rewards program is subject to termination without notice.